Hurricane Damage Roof Repair
A gust front works on a roof for a minute. A landfalling tropical system pushes at it for half a day, and the direction shifts as the storm passes so that every slope gets a turn on the windward side. That difference in duration is the whole reason hurricane damage does not look like thunderstorm damage. Fasteners loosen a little at a time. A sealant bond that gives up in the first hour leaves a shingle flapping for the remaining ten. And uplift does not press evenly — it concentrates at corners, along rakes and eaves, and around anything standing above the roof plane, so once the perimeter is breached the field peels back from there. That is why a hurricane repair spends most of its money on the edges of a roof rather than the middle.
Wind-driven rain goes where rain cannot
Water arriving horizontally at pressure gets into places gravity would never take it: under shingle courses, through ridge and soffit vents, around window and wall junctions, and behind flashing at chimneys and walls. This is why a roof that is largely intact after a storm can still soak a house, and why the repair scope is often much wider than the visible damage. The damage also keeps working after the sky clears — saturated decking, insulation and framing stay wet for days, and in warm humid air mold starts in that window. Drying the structure out is part of the repair, not an afterthought to it.
The single most effective upgrade against this is a sealed roof deck: taped or self-adhered seams over the sheathing so that even a roof stripped of its covering keeps water out of the building. It is a secondary water barrier rather than a roof, and it is the detail that most often separates a house that needed a new roof from one that needed a new roof and a new interior.
The order of work after landfall
Before landfall there is lead time, because the National Hurricane Center tracks these systems from formation onward, and those days are the window for a crew to secure loose flashing and clear drains — work for people equipped to be up there, not a reason to climb a ladder with a storm coming. Afterward, come back only when officials say the area is safe, and treat standing water, downed lines and damaged trees as live hazards. More people are hurt in the days after a hurricane than during it.
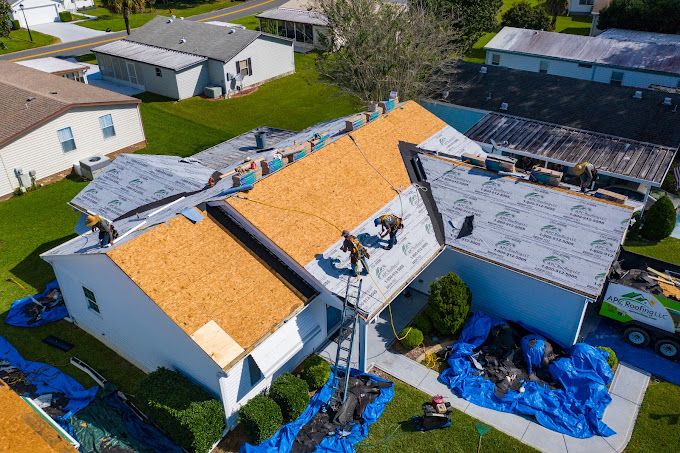
Then work the sequence. Document inside and out with dated photographs before anything is moved. Report the loss to your insurer. Get temporary protection over any opening — sized past the opening, fastened so wind cannot get under an edge, lapped so water runs over it rather than into it. Start removing wet materials. Permanent repair comes after the emergency dry-in, not instead of it.
Expect a queue, and plan around it
After a landfall, every roofer in the region is working at once, and crews, materials, permits and inspections all bottleneck together. Emergency protection is the priority and permanent work is scheduled behind it. The honest version of that conversation is a place in a sequence rather than a date, and it is worth asking any contractor for the former rather than accepting the latter. Repair itself starts by finding every point where water entered, which is rarely just the obvious bare patch. Decking gets checked for saturation and delamination and replaced where it has lost strength. Edge metal, ridge details and flashing are rebuilt rather than re-stuck, because those are the details the next storm tests first. Where a roof is being replaced rather than patched, current code requirements for fastening, underlayment and edge securement apply — and in Florida those requirements exist precisely because of what earlier storms taught.
Straight answers
After a hurricane, what roof damage does insurance cover, and what does it not?
The line that decides most hurricane claims is which way the water came from. Wind that opens the roof and the rain that follows it through is usually covered by your homeowners policy, subject to the hurricane deductible. Rising water is flood damage and needs a separate flood policy. Rain that gets in without wind first damaging the building is often excluded.
The line that decides most hurricane claims is not about the roof at all. It is about which direction the water came from.
Wind and wind-driven rain: usually your homeowners policy
If wind opened your building — tore shingles off, lifted a section of decking, put a limb through the roof, broke a window — and rain then came in through that opening, that is wind damage. Standard homeowners policies cover it, subject to your hurricane or windstorm deductible.
Rising water: not your homeowners policy
Storm surge and floodwater coming in from ground level are flood, and flood is excluded from every standard homeowners policy in the country. That coverage comes separately, through the National Flood Insurance Program or a private flood insurer. FloodSmart is the NFIP's consumer site and explains what the policy does and does not pay.
After a landfalling hurricane, a house can easily have both, which means two claims, two adjusters, and a fight over which policy pays for what. Documentation of high-water marks and of the roof opening is how that gets settled. Photograph both, early.
The wind-driven rain trap
Here is the exclusion that catches people. Many policies cover rain entering only through an opening the wind created. Rain driven horizontally through a soffit vent, around a window frame, or under a ridge cap on an intact roof may not be covered, because the building was never breached. Read your own policy on this before a storm rather than after.
What wind damage looks like on a roof
Asphalt shingles do not usually fail all at once. Wind lifts the tab, breaks the factory adhesive seal, and leaves the shingle lying flat again but no longer bonded. From the ground it looks fine. The tell is a horizontal crease across the shingle a few inches up from the bottom edge, and shingles that lift by hand instead of resisting. An unsealed shingle will leak in the next storm and blow off in the one after.
Other signs: missing tabs, exposed nail heads, lifted or torn ridge cap, displaced or cracked tile, damaged drip edge, and separation at the roof-to-wall flashing. On tile roofs, wind that lifts and drops tiles can crack them without moving them, and the underlayment beneath is what keeps the water out.
Deductibles are different in a named storm
Florida policies carry a separate hurricane deductible, usually 2 to 5 percent of the dwelling limit, triggered when the National Hurricane Center names the storm. Florida applies it on a calendar-year basis, so a second hurricane in the same year generally does not restart it.
One useful detail from Florida Statute 627.701: where a policy carries a separate roof deductible, it may not be applied to roof losses caused by a hurricane, to total losses under valued policy law, or to a tree or other hazard puncturing the roof deck.
Timing and the season
The Atlantic season runs June 1 to November 30, peaking in early September. NOAA's August 6, 2026 update kept its below-normal outlook, forecasting 7 to 13 named storms with 2 to 6 hurricanes and 0 to 2 major hurricanes, driven by a strengthening El Niño. A quiet seasonal outlook is not a forecast for your house — the season's first two storms both formed in the Gulf, and NOAA's own director noted that inland rainfall from a storm that never becomes a hurricane still does serious damage. The National Hurricane Center is the place to watch an active system.
Before the next one
Wind damage is one of the few kinds you can meaningfully reduce in advance. A sealed roof deck, high-wind nailing, fastened edge metal and secondary water resistance keep water out when covering material comes off. Florida's My Safe Florida Home program offers free wind mitigation inspections and grants toward qualifying upgrades, and that inspection form is also what your insurer uses to apply mitigation credits to your premium.
Coverage varies by policy and state. Read your own policy, and ask your agent what your hurricane deductible is in dollars before hurricane season, not during it.