Your roof needs work, and the estimate is a bigger number than you have sitting in savings. Maybe the leak showed up at a bad time, or the roof reached the end of its run before your budget was ready. You want to fix it now, but you don’t want to sign up for a loan you’ll regret.
That’s a reasonable worry. A roof is one of the biggest repairs most homeowners ever pay for, and roof financing comes with fine print that’s easy to miss. You should understand the terms before you sign anything.
APC Roofing offers financing through four lending partners: Aqua Finance, Fortifi, Hearth and Home Run Finance. We’re a roofing company, not a lender, so the lender sets the rate, the terms and the approval. We’re GAF Certified, licensed and insured, and we’ve been roofing homes since 2017. Call 866-995-0704 to start with a free inspection and estimate.
Ways homeowners pay for a roof
Most people use one of these routes, and some combine two.
- Savings, when the timing works.
- Insurance, when a covered event like a storm caused the damage. Your deductible and anything the policy doesn’t cover are still yours to pay.
- A home equity loan or line of credit from your bank or credit union. Both are borrowed against your house.
- Financing through your roofer, where a lending partner funds the loan and you repay the lender.
- A credit card, which is fast but usually the most expensive way to carry a balance this size.
Each has a different cost and a different consequence if money gets tight. There’s no single right answer, only the right one for your situation.
Questions to ask before you sign any roof financing
Read the terms, not just the monthly payment. Ask for these answers in writing:
- What’s the interest rate, and is it fixed or variable?
- How long is the term, and what will the loan cost in total, not just per month?
- Is there a promotional or deferred-interest period? If so, what happens the day it ends?
- Are there origination or processing fees?
- Is there a penalty for paying it off early?
- When is the first payment due?
- Does the loan put a lien on your home?
- Who actually holds the loan?
The deferred-interest question is the one people skip most. On some promotional plans, if the balance isn’t paid off before the promo period ends, interest gets charged back to the start of the loan. That’s how those products are designed, so it’s worth knowing before you choose one.
Take the paperwork home and read it before you decide. A lender who won’t put the terms in writing is telling you something.
What drives the amount you’ll finance
The size and steepness of your roof set most of the labor and material. Layers of old roofing to remove, damaged decking found underneath, and the number of valleys, vents and chimneys all add to the job. Material matters a lot, too. A 3-tab shingle costs less than an architectural or impact-rated one, and tile and metal are different again.
When you’re comparing estimates, compare the scope line by line before you compare the totals. A bid far below the others is usually describing less work.
Check whether insurance applies first
If a storm caused the damage, find out whether it’s a covered loss before you apply for a loan. It could change how much you need to borrow. Nobody can promise you a claim approval, but it’s worth knowing before you commit to financing. Our insurance roof claims page explains how that process works.
Repair now, or replace later?
Sometimes the right answer is a repair that buys you time to save for a replacement. If the roof still has life in it, that can be a smart call, and we’ll tell you if that’s where you are. Our roof repair page covers what that looks like.
When a roof is already leaking, though, waiting usually costs more. Water soaks decking and insulation and stains ceilings, and that interior repair work isn’t roofing at all.
How it works with APC Roofing
- Book your free inspection. Call 866-995-0704 or request a free online estimate.
- Get a clear, honest assessment and estimate. You’ll know what the roof needs and what it costs before you think about financing. If you’d like to finance, you can apply with one of our lending partners.
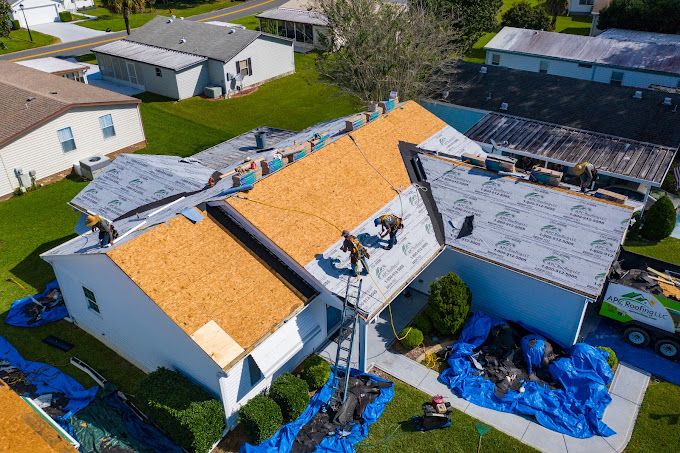
- Your roof gets done and the site cleaned up. Many residential roofs are done in a single day, and we clean up like we were never there.
You can read more on our financing page, or see roof financing in Orlando.
Roof financing questions
Do you offer financing for a new roof?
Yes. Financing is available through Aqua Finance, Fortifi, Hearth and Home Run Finance. The lender handles the application, the approval and the terms.
What rate will I get?
That’s up to the lender, based on your application. We don’t set rates or terms, and we won’t guess at them.
Can I get roof financing with bad credit?
Approval is the lender’s call, based on your full application, so we can’t promise one. Applying with a lending partner is the only way to know for sure.
Can I finance a roof repair, not just a replacement?
Ask about your specific job. Whether a smaller repair qualifies depends on the lender’s rules.
Get the roof done on terms you understand
You don’t have to choose between a leaking roof and a loan you’re unsure about. Get the facts on the roof first, then read the terms with clear eyes.
That’s how you end up with a sound roof, a dry house and a payment plan you actually understand. Call 866-995-0704 to book your free inspection, or start your estimate online.