The storm’s gone, the yard is full of shredded leaves, and your neighbor already has a roofer’s sign in the grass. You’re not sure if your roof is damaged, whether it’s worth filing a roof insurance claim in Overland Park, or what happens once you do. Nobody wants to fight with an insurance company, and nobody wants to miss damage that shows up as a leak next spring.
You deserve to understand your own claim before anyone asks you to sign anything. It’s a process with clear steps, and you stay in charge of every one of them.
APC Roofing is a GAF Certified roofing contractor, licensed and insured, in business since 2017. Your inspection is free. Call 913-398-5020 and a roofer will inspect the whole roof, photograph and measure any damage, and tell you plainly whether it looks like something worth a claim.
Who does what on a roof insurance claim in Overland Park
It helps to know the roles up front.
You own the policy. You file the claim with your insurance company, talk with your adjuster, decide on a contractor and pay your deductible. The claim is between you and your insurer.
Your insurance company sends an adjuster to inspect the damage and decides what the policy covers.
A roofer documents the damage, writes a repair or replacement estimate and can meet the adjuster on the roof to point out what was found. A roofer doesn’t decide your claim and doesn’t speak for you to your insurance company.
That’s how we work. We give you photos, measurements and a written estimate, and we work with your adjuster during the inspection. Trust matters, and keeping the claim yours is part of that.
Steps after a hail or windstorm in Overland Park
1. Stay off the roof and look from the ground
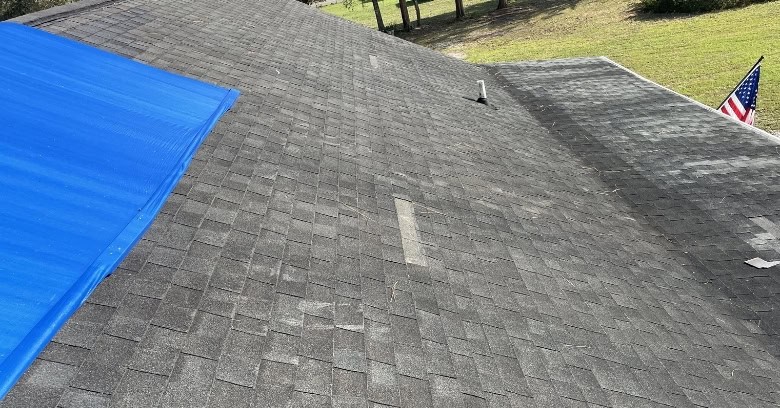
Look for missing or creased shingles, dented gutters and downspouts, dings on metal vents and granules washed out at the bottom of the downspouts. Take dated photos of anything you see, inside and out. If water is coming in, put down a bucket and move what you can out of the way.
2. Get a roof inspection
A free inspection tells you whether there’s damage before you call your insurer. Hail damage on shingles is often hard to see from the ground, and it’s easy to overlook or overestimate. Knowing what’s there helps you decide if a claim makes sense.
3. Read your policy
Check your deductible, any separate wind or hail deductible, and the deadline for reporting damage. Some policies pay replacement cost and some pay actual cash value, which subtracts depreciation for the roof’s age. Your insurance agent can explain which you have.
4. File the claim yourself
Call your insurance company or file online. You’ll get a claim number and an adjuster will be assigned.
5. Meet the adjuster
The adjuster inspects the roof and writes up what they find. It helps to have your roofer there so the adjuster sees everything that was documented. If the adjuster’s report misses something, your roofer’s photos and measurements are the record you can share with your insurer.
6. Review the decision and schedule the work
Once the claim is decided, you’ll get your insurer’s scope of work and payment details. Compare it with your roofer’s estimate and ask your insurer about anything you don’t understand. Then the repair or replacement gets scheduled.
About your deductible
Your deductible is your responsibility, every time. Be wary of anyone who offers to waive it, cover it, or bury it somewhere in the price of the job. Honest roofers don’t make that offer, and it puts you in a bad spot with your insurer. Also read carefully before you sign any contract that gives a contractor control over your claim or your insurance payment.
When a claim doesn’t make sense
Sometimes the damage is real but small, and the repair costs less than your deductible. Sometimes the roof is simply old and worn rather than storm-damaged, and a policy won’t cover normal aging. In those cases, an honest inspection saves you a claim on your record for nothing. If you need to pay for work yourself, financing is available through Aqua Finance, Fortifi, Hearth and Home Run Finance.
How it works
- Book your free inspection. Call 913-398-5020 or request a free estimate online.
- Get a clear, honest assessment and estimate. You’ll get photos and measurements of any storm damage and a written estimate you can share with your insurer.
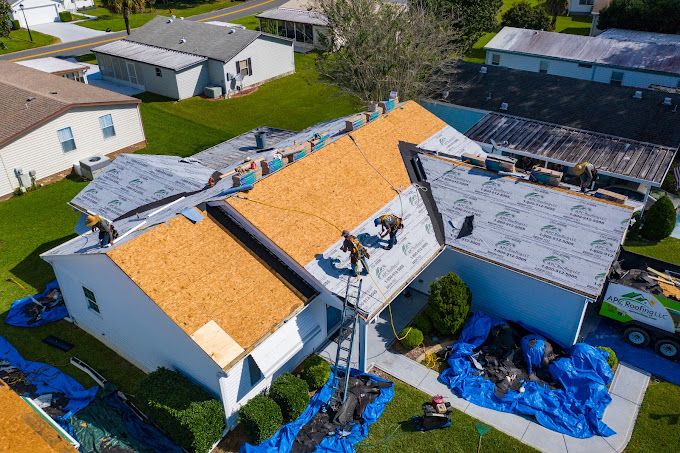
- The work gets done and the site gets cleaned up. Once you’ve made your decision, the repair or replacement is scheduled, and the crew cleans up before they leave.
Hail damage doesn’t always leak right away. Bruised shingles can lose granules and crack over the next few seasons, and most policies have a time limit for reporting storm damage. Getting the roof checked soon after a storm keeps your options open.
Roof insurance claim questions
Will filing a claim raise my premium?
That comes down to your insurer, your policy and your claim history. Your agent is the one to ask, and it’s a fair question to ask before you file.
Do I need a roofer before I call my insurance company?
You don’t have to have one, but an inspection first tells you whether there’s damage worth claiming and gives you documentation for the adjuster.
Can you send the bill straight to my insurance company?
Your insurer pays according to your policy, usually to you and sometimes to your mortgage company as well. You pay your deductible. We’ll walk you through how payment works for your job.
What if my claim is denied?
Ask your insurer for the reason in writing and what their review process is. Our photos and measurements are yours to share with them.
Get your roof inspected after the storm
Call 913-398-5020 or book your free inspection online. For more on what storms do to a roof, see storm damage in Overland Park, hail damage roof repair and wind damage roof repair.
You’ll come out the other side with a sound roof, a claim you understood from start to finish, and no surprises on the bill.