The hurricane has moved on, and now you’re dealing with what it left behind. Maybe a section of shingles is gone and there’s a stain spreading on the ceiling. Maybe the roof looks fine, but you heard things hitting it all night. You need hurricane damage roof repair in Clermont, and you need someone who’ll tell you straight what the storm did.
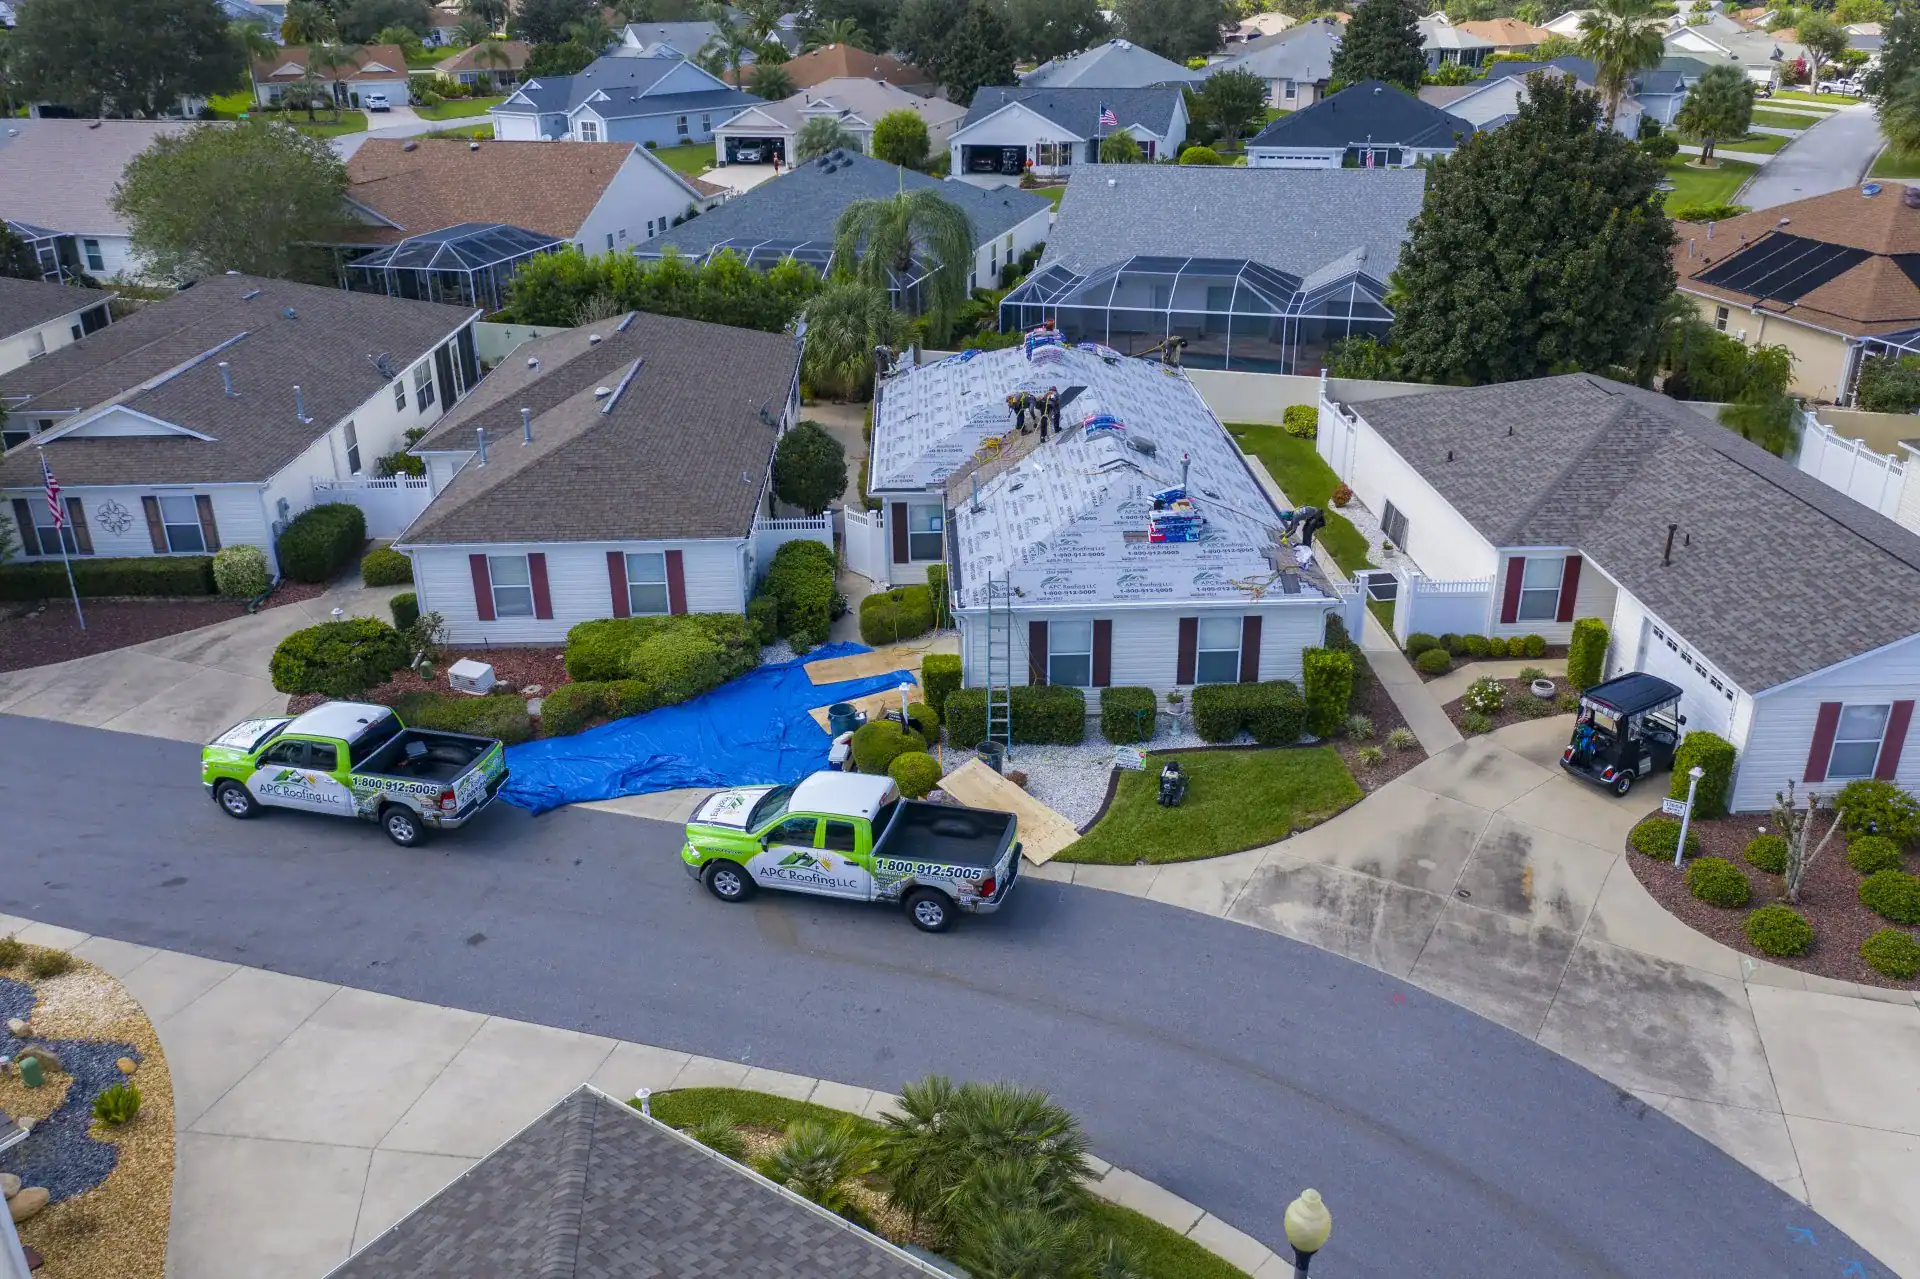
The days after a hurricane are hard. Everyone in the area needs help at once, insurance feels confusing, and every other truck on the street seems to belong to a roofer you’ve never heard of. You deserve a local roofer who’ll still be here when the next season starts.
APC Roofing is headquartered in Clermont and has served Central Florida since 2017. We’re GAF Certified, licensed in Florida (CCC1337030) and insured, and the inspection is free. Call 407-270-1129.
What a hurricane does to a roof inland
Clermont is far enough inland that storms usually arrive weaker than they were at the coast. They can still bring tropical-storm or hurricane-force gusts for hours, plus rain that comes in sideways and keeps coming. Long exposure is the problem. A roof that would shrug off one strong gust can loosen under a whole night of them.
Wind pulls hardest at the edges, corners, ridges and overhangs of a roof. That’s where damage usually starts, and once one piece lifts, the wind gets underneath the next.
Shingle roofs
Shingles lose their adhesive seal, flap, crease and tear off. Ridge caps peel away. Even shingles that are still in place may have come unsealed and will lift in the next strong wind. With shingles gone, rain hits the underlayment directly, and that layer isn’t meant to be the roof for long.
Tile roofs
Tiles can loosen, slide or crack, especially at the hips, ridges and edges. Flying debris breaks tile too. Under a tile roof, wind-driven rain can get past displaced tiles and test the underlayment, which is the real waterproofing on these roofs.
Metal and flat roofs
Metal panels and trim can pull loose at fasteners and edges. On flat and low-slope roofs over porches and additions, wind can peel the membrane back at its edges or lift seams.
Flashing, soffits and gutters
Flashing at walls and chimneys gets bent or pulled away. Soffit panels can blow out and let wind-driven rain into the attic. Gutters get torn loose or crushed by limbs.
Hurricane damage you won’t see from the ground
A lot of hurricane damage hides. Unsealed shingles look flat on a calm day. Cracks in tile can sit under the row above. Rain that got in under lifted flashing can soak insulation for weeks before a stain shows up. That’s why a careful inspection, with photos from the roof and a look in the attic when it’s reachable, matters after a hurricane even when nothing is dripping. Our wind damage roof repair page goes deeper on what wind does to each part of a roof.
Your hurricane claim, step by step
You file the claim with your insurance company and you pay your deductible. Many Florida homeowners policies carry a separate hurricane deductible that’s figured differently from the regular one, so check your policy or ask your agent what yours is. We inspect the roof, document the damage with photos, provide a written estimate and work with your adjuster. Your insurance company makes the coverage decision.
Keep a folder of everything: photos, dates, receipts for anything you bought to protect the house, and every letter from the insurance company. Our insurance roof claims page walks through the process in more detail.
After a hurricane, be wary of anyone who offers to waive or cover your deductible, pushes you to sign on the spot or asks for a big payment up front.
Hurricane damage roof repair in Clermont: repair or replace?
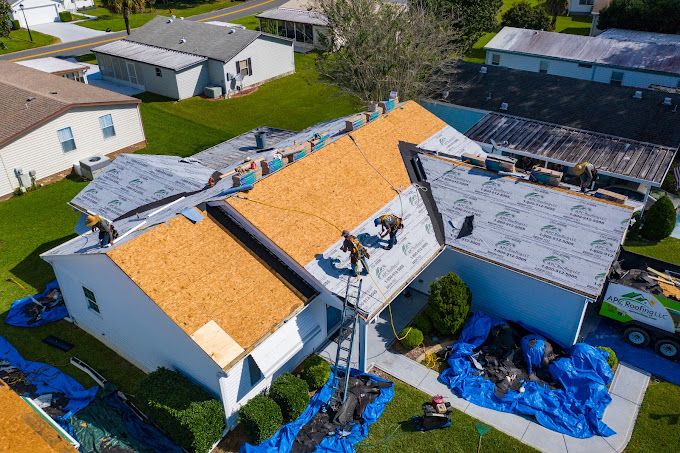
If the damage is limited to a few areas and the rest of the roof is in good shape, a repair is often the right call. If large sections are gone, the roof was already near the end of its life, or damage is spread across several slopes, replacement may make more sense. You’ll see the photos and hear the reasoning either way. If your roof is tile, our tile roof repair page explains what tile repairs involve.
After a widespread storm, materials and crews can be in short supply for a while. You’ll get an honest timeline rather than a promise that sounds good on the phone.
How it works
- Book your free inspection. Call 407-270-1129 or request a free online estimate.
- Get a clear, honest assessment and estimate. You’ll get photos of the damage and a written estimate you can share with your adjuster.
- Your roof gets repaired or replaced and the site gets cleaned up.
If insurance doesn’t cover everything, financing is available through Aqua Finance, Fortifi, Hearth and Home Run Finance.
Waiting after a hurricane carries real cost. Every rain that falls on an open or weakened roof adds water to the decking and insulation, and the next storm in the season will find the same weak spots.
Hurricane roof questions from Clermont homeowners
How soon after a hurricane should I get my roof inspected?
As soon as it’s safe and you reasonably can. Early documentation helps your claim, and small damage is easier to fix before more rain gets in.
What’s a hurricane deductible?
Many Florida policies have a separate deductible for hurricane damage, often figured as a percentage of the home’s insured value instead of a flat amount. Your policy or your agent can tell you exactly what yours is. You’re responsible for paying it.
My roof looks fine. Should I still have it checked?
Yes. Unsealed shingles, cracked tile under the row above and loose flashing often don’t show until the next storm.
Should I get my roof checked before hurricane season?
It’s a good idea, especially if the roof is older or took damage last year. Hurricane season runs June 1 through November 30, and a free inspection in spring gives you time to fix weak spots before it starts.
Book your hurricane damage inspection in Clermont
Call 407-270-1129 or book online. The goal is a roof that’s sound again before the next storm, a dry house and a clear picture of where you stand with your insurance.