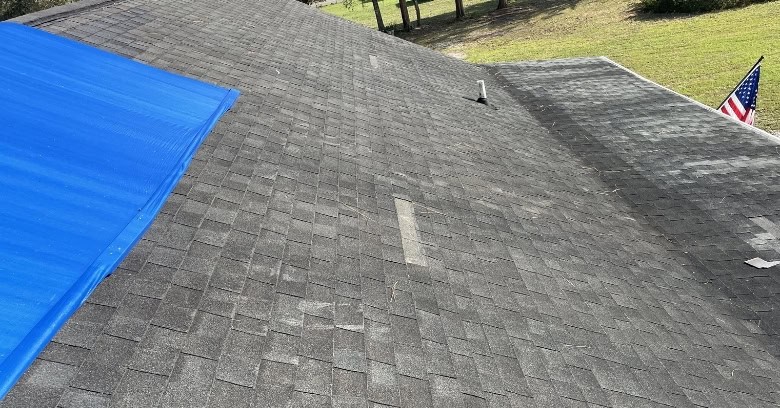
The storm passed, and now there are shingles in the yard, a stain on the ceiling or a tile you can see sitting crooked from the street. You’re wondering whether it’s worth filing a claim, how roof insurance claims in Orlando actually work, and who you can trust to tell you what’s really damaged.
That uncertainty is the hardest part. Insurance paperwork is confusing, you’ve heard stories about contractors who promise the moon after a hurricane, and you don’t want to make a mistake that costs you. You deserve a clear picture of who does what, with no pressure and no promises nobody can keep.
APC Roofing inspects and repairs storm-damaged roofs across the greater Orlando area, from Clermont and Kissimmee to Sanford and Altamonte Springs. We’re GAF Certified, licensed in Florida (CCC1337030) and insured. Your inspection is free.
How roof insurance claims in Orlando work
Every policy is different, but the basic path looks like this:
- You get the roof inspected. A roofer checks for damage and documents what’s there, so you know whether there’s anything worth claiming.
- You file the claim. You contact your insurance company and report the damage. The policy is between you and your insurer, so this step is yours.
- An adjuster inspects. Your insurer sends an adjuster to look at the roof and decide what the policy covers.
- You get the insurer’s decision. If the claim is approved, the insurer pays for covered damage, minus your deductible.
- The roof gets repaired or replaced. You pick the contractor and pay your deductible.
Florida has tightened its rules in recent years, including how long you have to report a claim after a storm. Check your policy or ask your agent so you don’t miss a deadline. Many Florida policies also carry a separate hurricane deductible that works differently from the standard one, so it’s worth knowing which applies before you file.
What APC Roofing does on an insurance claim
Here’s our part, and it’s an important one.
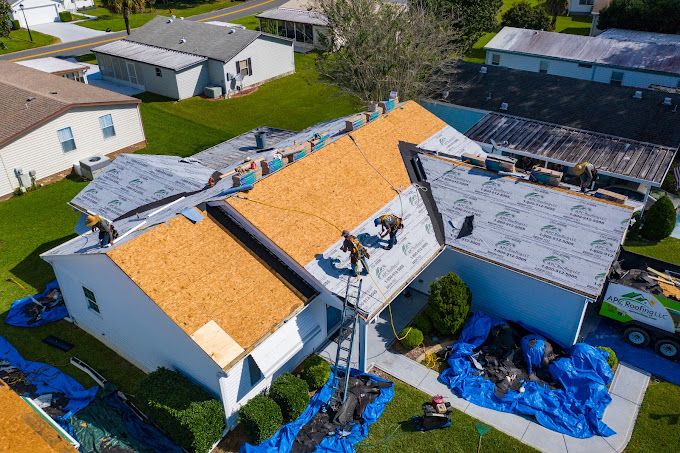
We inspect the whole roof, not just the spot you noticed. Damage gets photographed and measured slope by slope, so there’s a clear record of what the storm did. You get that documentation and a written estimate for the repair or replacement the damage calls for.
When your adjuster comes out, we can meet them at the roof and walk through what we found. We work with your adjuster so the damage on your roof is clearly accounted for.
What you handle, and what we won’t do
You file your own claim, and you pay your own deductible. That’s your responsibility under your policy, so be wary of any contractor who offers to waive, cover or rebate it. If a roofer tells you they’ll make your deductible disappear, that’s a red flag, not a favor.
There are also things a roofer shouldn’t do. We won’t interpret your policy or tell you what your coverage includes. Questions about coverage, a denied claim or a dispute belong with your insurance agent, a licensed public adjuster or an attorney. A roofer’s job is the roof: documenting the damage accurately and fixing it right.
Choosing roofing companies that deal with insurance claims
After a big storm, crews from out of the area show up fast. Many are legitimate. Some aren’t. A few checks help:
- Look up the contractor’s Florida license on myfloridalicense.com.
- Ask for proof of liability and workers’ compensation insurance.
- Be wary of anyone offering a “free roof,” cash, gifts or a deductible deal in exchange for an inspection or a claim.
- Don’t sign anything you haven’t read, especially on the day of a storm.
- Prefer a company with a local office that’ll still be around next year.
Storm damage on Orlando roofs
Central Florida roofs mostly take damage from wind, wind-driven rain and falling limbs. Wind lifts and creases shingles, cracks or shifts tile and pulls up flashing and edge metal. Some of that damage is easy to miss from the ground, especially creased shingles that lie back down after the storm. For more on what to look for, see our storm damage roofing, hurricane damage roof repair and wind damage roof repair pages.
Commercial property owners go through the same basic process. You file with your carrier, and we document the damage on your building and provide an estimate.
How it works with APC Roofing
- Book your free inspection. Call 407-270-1129 or request a free estimate online. Our roof inspection page explains what we check.
- Get a clear, honest assessment and estimate. You’ll get photos, measurements and a written estimate. If there’s no storm damage worth claiming, you’ll hear that too.
- Your roof gets done and the site gets cleaned up. Once your claim is settled and you’re ready, the work gets scheduled and the crew cleans up when it’s done.
Roof insurance claim questions from Orlando homeowners
Should I call my insurance company or a roofer first?
Many homeowners have the roof inspected first so they know whether there’s real damage before filing. Either order works. Just don’t wait so long that you miss your policy’s reporting deadline.
Will you file the claim for me?
No. You file the claim with your insurance company. We provide the documentation and estimate and work with your adjuster.
Can you help with my deductible?
No. Your deductible is your responsibility under your policy, and an honest roofer won’t offer to pay, waive or rebate it.
What if my claim is denied?
We can walk you through what our inspection found, but we can’t advise you on your policy. Your agent, a licensed public adjuster or an attorney can help you decide what to do next.
A repaired roof and a clear head
Waiting on storm damage can turn a covered repair into a bigger problem: water works into the decking, and reporting deadlines get closer. Get the roof looked at soon after the storm, and you’ll know exactly what you’re dealing with, have the documentation in hand and end up with a sound roof and no surprises. Call 407-270-1129 to book your free inspection. Trust matters.