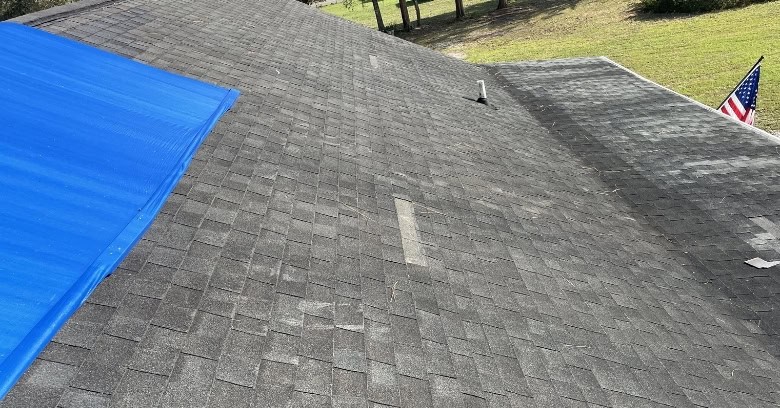
The storm has moved on, but you’ve got a creased shingle flapping near the ridge, a few broken tiles in the yard or a new stain on the bedroom ceiling. Now you’re facing an insurance claim, and you aren’t sure what to do first, what the adjuster will look for or whether the damage is even big enough to report. Insurance roof claims in Palm Coast can feel like a lot of paperwork stacked on top of a leak.
It’s normal to feel uneasy about it. You’re dealing with a big company over a big expense, and after every major storm, crews nobody’s heard of start knocking on doors with promises. You deserve a plain explanation of how the process works and a local roofer who stays in their lane.
APC Roofing is GAF Certified, licensed in Florida (CCC1337030) and insured. We inspect storm-damaged roofs across the Daytona Beach area, Palm Coast included, and the inspection is free.
How insurance roof claims in Palm Coast work
A claim has three parties, and each one has a different job.
You own the policy, so you file the claim with your insurance company and you pay your deductible. You also decide which roofer does the work.
Your insurance company sends an adjuster, reviews the damage and decides what your policy covers.
Your roofer inspects the roof, documents the damage, writes an estimate for the repair or replacement and works with your adjuster so the damage on your roof is clearly accounted for. That’s our part. We don’t decide coverage, and we can’t promise what your insurer will pay.
Keeping those roles straight protects you. A roofer who claims they can guarantee an approval, or who wants to take over your claim, is promising something they can’t deliver.
The first few days after a storm
If water is coming in, deal with the inside of the house first. Move furniture and electronics, put a bucket under the drip and, if water is near a light fixture or outlet, switch that circuit off at the breaker.
Then start your own record. From the ground, photograph each side of the house, anything that came off the roof and any interior stains. Write down the date of the storm. Keep receipts for anything you spend to protect the house, since your insurer may ask for them.
Read your policy, or call your agent, and find out how soon damage needs to be reported. Don’t climb onto the roof yourself. Wet shingles and tile are slick, and a trained roofer can see more in ten minutes up there than you can in an hour.
What a good damage record includes
The adjuster is going to look at your roof either way. A careful record from your roofer makes sure nothing gets missed. A useful one usually covers:
- Photos of every slope, not only the damaged one, so the whole roof is on file
- Close-ups of each damaged spot with something in the frame for scale
- Damage to flashing, vents, pipe boots, ridge caps and gutters, which is easy to overlook
- Attic signs like daylight through the decking, damp wood or wet insulation
- Interior stains tied back to where the water is getting in
It should also separate storm damage from ordinary wear. A Palm Coast roof that’s been through years of sun and salt air will have some aging that has nothing to do with last week’s storm. Mixing the two up doesn’t help you. You get a copy of everything we document.
Coastal storms and the roof over your head
Palm Coast faces the Atlantic, and that shapes the kind of damage you’ll see. Hurricanes and tropical storms bring hours of high wind from shifting directions. Nor’easters in the cooler months can blow steady onshore wind and rain for a day or more, which works water under any shingle or tile that’s already loose. Summer thunderstorms add sudden gusts and occasional hail.
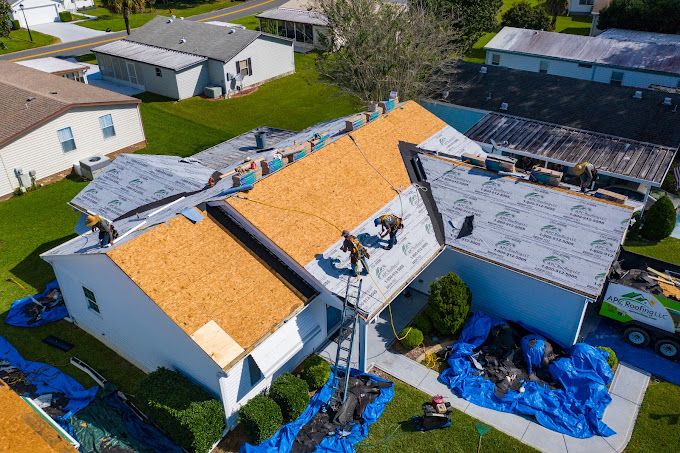
Shingle roofs tend to show lifted, creased or missing shingles along the edges and ridge. Tile roofs crack or slip, and the underlayment beneath them can be damaged even when most of the tile looks fine. Metal roofs can lose fasteners or have panel edges pulled up. If your damage is mostly from wind, our page on wind damage roof repair in Palm Coast goes into what that repair involves.
Be careful at the front door
After a big storm, you may get visits from crews offering to start right away. Take your time. Don’t sign anything at the door, ask to see a state contractor license and proof of insurance, and get a written estimate you can read at your kitchen table.
Be wary of anyone who offers to waive or cover your deductible, or who tells you the roof will cost you nothing. Your deductible is part of your policy, and an honest roofer won’t offer to make it disappear.
After your insurer makes a decision
Once the adjuster’s report comes back, compare it with your roofer’s estimate. If they line up, the work can be scheduled. If something on the roof seems to be missing from the insurer’s report, ask your insurance company how to have it looked at again. We can provide our photos and estimate for that conversation.
If you choose to do more than the claim covers, or the inspection finds wear the policy doesn’t include, that part is your call. Financing is available through our lending partners if it helps, and the roof financing page for Palm Coast explains how that works.
How it works with APC Roofing
- Book your free inspection. Call 386-259-8425 or request a free estimate online.
- Get a clear, honest assessment and estimate. You’ll get photos and a written estimate showing what the storm did and what it will take to fix it, ready to share with your adjuster.
- Your roof gets done and the site gets cleaned up. Once you’re ready to move ahead, the crew does the work and cleans up before leaving. Many residential projects are finished in a single day.
Small storm damage doesn’t stay small for long in Florida. A lifted shingle or cracked tile can let rain into the decking all summer before a stain ever shows on the ceiling, and by then the repair is bigger than it needed to be.
Roof insurance claim questions from Palm Coast homeowners
Do I need a roof inspection before I file a claim?
It isn’t required, but many homeowners like knowing whether there’s real storm damage before they report it. Whether and when to file is your decision.
Will you file the claim for me?
No. You file your own claim and pay your own deductible. We document the damage, write the estimate and work with your adjuster.
What if the inspection doesn’t find storm damage?
Then that’s what you’ll hear. You’ll still get an honest read on the roof’s condition and whether anything needs attention.
Can you repair my roof even if I don’t file a claim?
Yes. Plenty of repairs are handled without insurance, and the estimate is the same either way.
Get your Palm Coast roof looked at
Call 386-259-8425 to book your free inspection. You’ll know what the storm did, what it takes to fix it and what to bring to your adjuster. That’s how you end up with a sound roof, a dry house and a claim you understood from start to finish. For everything else we handle in town, see our specialty roofing services in Palm Coast.