The storm passed through overnight. This morning there are shingle pieces in the yard, dents in the gutters, and a neighbor mentions that a roofer already knocked on their door. You’re wondering whether you have damage, whether it’s worth filing a claim, and how insurance roof claims in Kansas City actually work, without getting pushed into signing something on the front porch.
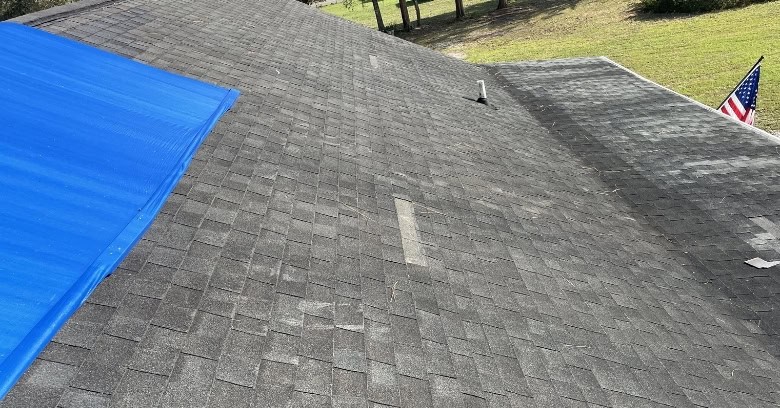
That uncertainty is normal. Most homeowners only go through a roof claim once or twice, and the process isn’t obvious the first time.
APC Roofing is a GAF Certified roofing contractor, licensed and insured. We inspect storm-damaged roofs for free, document what we find and give you a written estimate. You stay in charge of your claim.
Who does what on a roof insurance claim
It helps to know the roles before you start.
You own the policy. You decide whether to file, you file the claim with your insurance company, and you pay your deductible. The claim is between you and your insurer.
Your insurance company sends an adjuster to inspect the damage and decides what the policy covers.
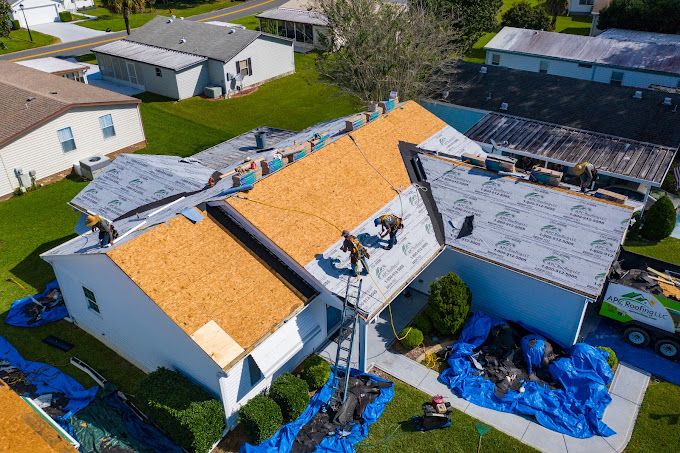
Your roofer inspects the roof, documents the damage with photos, writes an estimate for the repair or replacement, and can be on the roof when the adjuster inspects so the damage gets seen. Then the roofer does the work.
APC Roofing does that roofer’s part. We won’t take over your claim or speak for you to your insurance company.
How insurance roof claims in Kansas City work, step by step
1. Check from the ground, safely
Look for shingle pieces in the yard, dents in gutters, downspouts and metal vents, and granules washing out of the downspouts. Check your ceilings and attic for new stains. Stay off the roof.
2. Get a free roof inspection
A roofer can tell you whether there’s real storm damage before you file. If the roof looks fine, you may not need a claim at all, and that’s worth knowing. Our hail damage roof repair page explains what hail does to different roofs.
3. Review your policy
Look at your deductible, whether your policy pays replacement cost or actual cash value, and any deadline for reporting damage. Many policies set a time limit, so don’t wait months to look into a storm.
4. File your claim
If there’s damage and you decide to file, contact your insurance company and open a claim. Share the photos you’ve taken.
5. Meet the adjuster
The adjuster inspects the roof and writes up what the policy covers. We can be there so the damage we documented gets seen.
6. Review the settlement
Compare the adjuster’s report with the roofer’s estimate. If something seems missing, ask your insurer how to send more documentation. We can provide photos and written details for you to submit.
7. Schedule the work
Once you’ve decided how to proceed, the repair or replacement gets scheduled. You pay your deductible as part of the project.
What hail and wind do to Kansas City roofs
Spring and early summer storms bring the most claims here. Hail bruises shingles, knocks off granules and dents metal. Wind lifts and creases shingles or tears them off. Damage isn’t always visible from the ground, and some of it doesn’t leak until months later, which is why an inspection after a big storm is worth it even if nothing is dripping. For a fuller look at storm work, see our storm damage roofing in Kansas City page.
Protecting yourself from storm chasers
After a big hailstorm, out-of-town crews often show up in Kansas City neighborhoods. Most homeowners can protect themselves with a few habits:
- Be wary of anyone who offers to waive your deductible. It’s yours to pay.
- Don’t sign anything on the spot, especially a contract or form you haven’t read.
- Ask for proof of insurance and a local address.
- Get the estimate in writing before work starts.
A trustworthy roofer will give you time to think, explain what they found with photos and leave the claim decisions to you.
If your claim doesn’t cover a full replacement
Sometimes the claim is denied, or it covers repairs but not a new roof. If your roof still needs work, we’ll give you an honest estimate either way. Financing is available through Aqua Finance, Fortifi, Hearth and Home Run Finance. See our roof financing in Kansas City page.
How it works with APC Roofing
- Book your free inspection. We’ll inspect the whole roof and document any storm damage with photos.
- Get a clear, honest assessment and estimate. You’ll get our findings and a written estimate. If there’s no storm damage, we’ll tell you that, too.
- Your roof gets done and the site cleaned up. After your claim is settled and you’ve decided how to proceed, the work gets scheduled, and many residential roofs are finished in a single day.
Waiting too long after a storm can make a claim harder, and hidden damage tends to grow. A free look now gives you facts to work with.
Insurance roof claim questions
Should I call a roofer or my insurance company first?
Many homeowners have a roofer inspect first to find out whether there’s damage worth filing for. Either order works. Just don’t wait past your policy’s reporting deadline.
Will filing a claim raise my premium?
That depends on your insurer and your policy. Your agent is the right person to ask.
Do I have to pay my deductible?
Yes. The deductible is your responsibility on every claim. Be wary of anyone who offers to waive your deductible.
Can you meet with my adjuster?
Yes. We can be on the roof during the adjuster’s inspection to point out the damage we documented.
Get your storm damage checked
Call 913-398-5020 or request your free estimate online to book your free inspection.
When it’s done, you’ll have a sound roof and a claim you understood from start to finish.